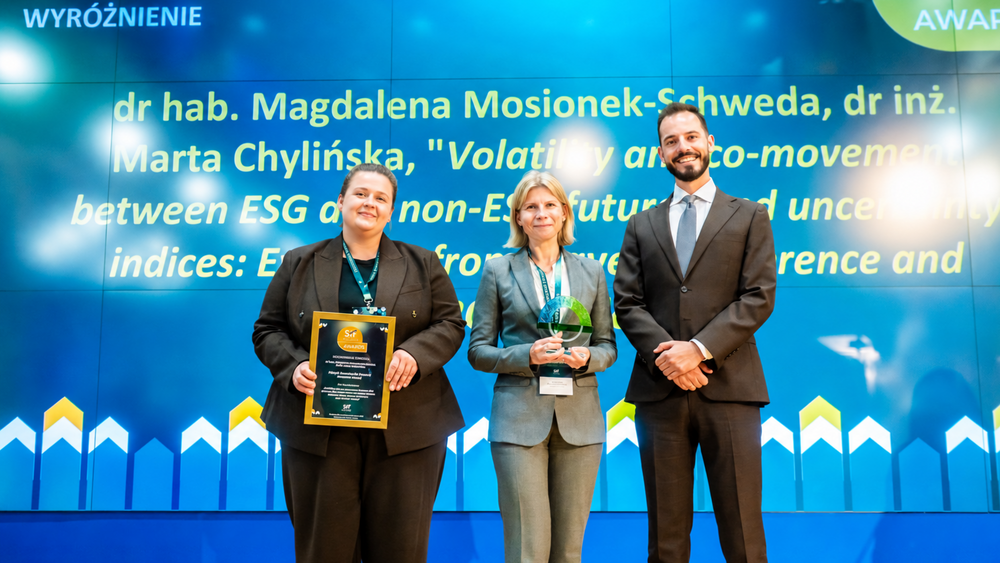
The award-winning publication, entitled “Volatility and Co-Movement Between ESG and Non-ESG Futures and Uncertainty Indices: Evidence from Wavelet Coherence and GARCH Models”, was published in the journal Research in International Business and Finance (DOI: 10.1016/j.ribaf.2026.103509).
The authors investigated whether futures contracts based on ESG indices behave differently from futures contracts linked to traditional stock market indices under conditions of increasing uncertainty. The analysis covered relationships between ESG and non-ESG markets and the most important measures of uncertainty, such as the VIX volatility index, the GPR geopolitical risk index, and the EPU economic policy uncertainty index. The study employed GARCH models and wavelet coherence analysis, making it possible to assess how the examined relationships change over time and across different investment horizons. The findings indicate that ESG contracts are not isolated from overall market risk. However, they may display a different short-term and medium-term volatility profile, as well as a certain degree of relative resilience during periods of severe turbulence.
The study’s results are significant from both scientific and practical perspectives, particularly in the context of portfolio diversification, risk management and the design of investment strategies that take ESG factors into account.
We warmly congratulate the authors and wish them continued success in their research careers!